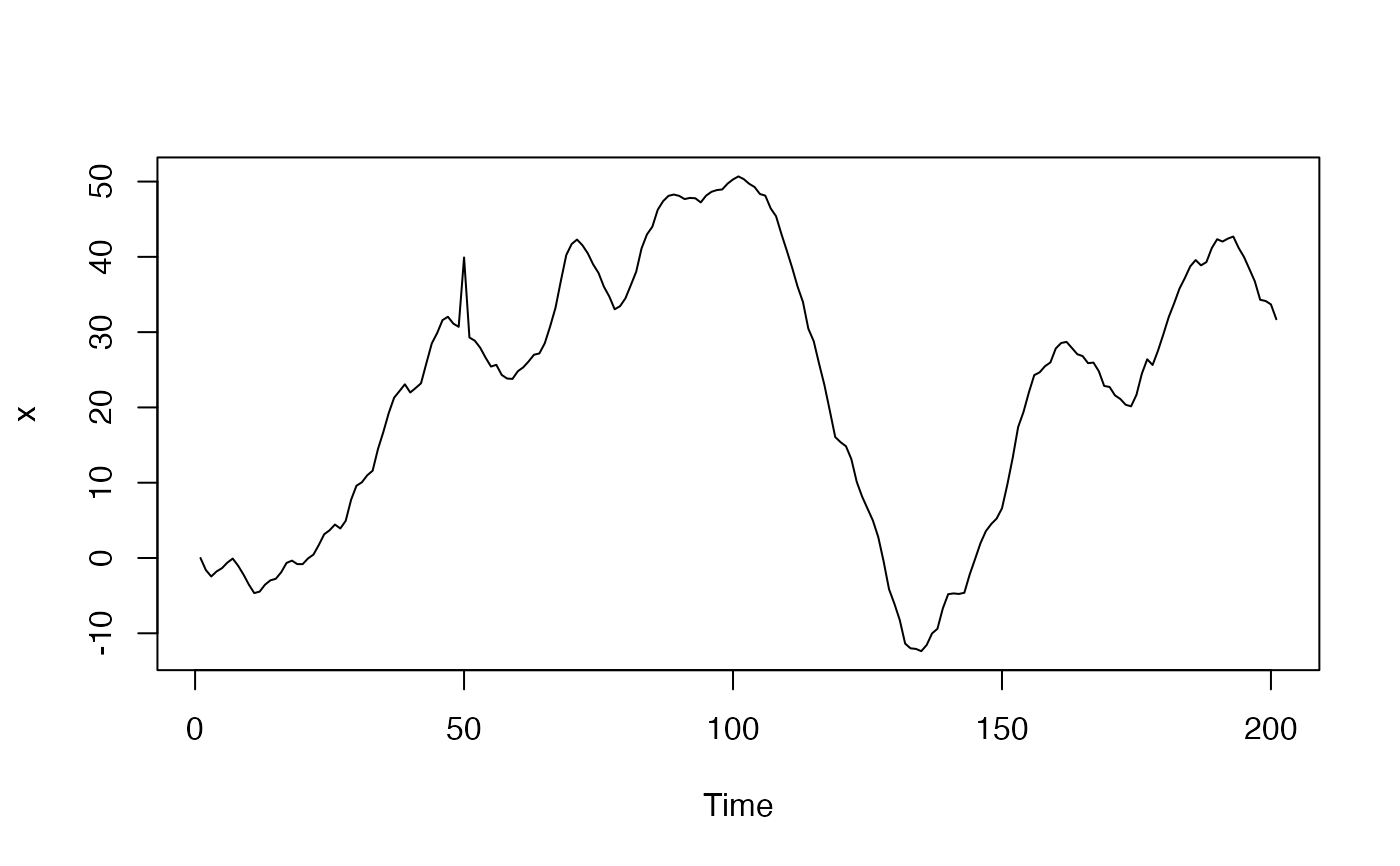
Identifies outliers in univariate time series using the algorithm lookout.
Source:R/lookout_ts.R
lookout_ts.RdThis is the time series implementation of lookout which identifies outliers in the double differenced time series.
Arguments
- x
The input univariate time series.
- scale
If
TRUE(the default), the data are scaled before the bandwidth and density estimates are computed: withmvscale()whenold_version = FALSE, so that the columns are approximately uncorrelated with unit scale, or by scaling each column to the range[0, 1]whenold_version = TRUE.- ...
Other arguments are passed to
lookout.